The “Trump Tariff Turmoil” is creating a market disturbance and uncertainty, which is developing rapidly into a position akin to the COVID lockdown position of March 2020. We can see the similarities in the chart below from early 2020:
LOCKDOWN UNCERTAINTY: 1st January 2020 to 7th April 2020
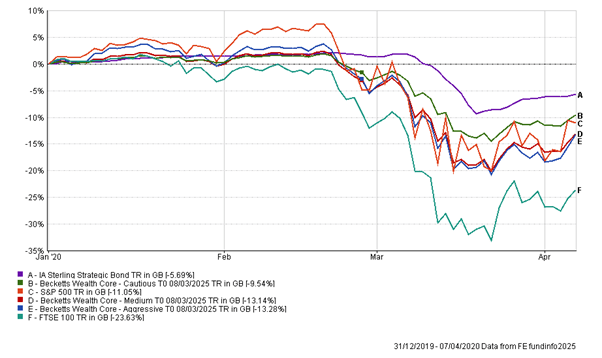
In this very uncertain environment, there was indiscriminate sell-off across all main asset classes, including fixed income, represented here by the Investment Association (IA) Sterling Strategic Bond sector index.
As we can see, the S&P500 sold off by ~11% (having been down more than 20% earlier in March 2020). with the FTSE100 down ~24% (having been down by 30%+ earlier in March 2020).
Fast forward to:
GLOBAL TRADE UNCERTAINTY: 1st January 2025 to 7th April 2025
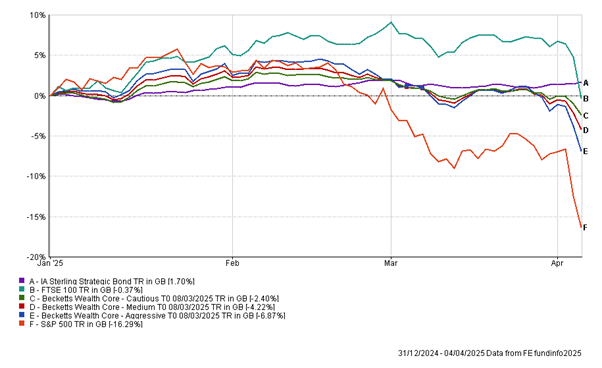
As we can see, US markets (represented above by the S&P500) had already begun to trend downwards in early 2025 in wake of the uncertainty.
We explained in our post on Friday last week, the scale and extent of the announced tariffs were unexpected and compounded latterly by reciprocated Chinese measures.
There are differences above in the two positions as:
- It is the US equity markets that have taken the brunt of the sell off to this point;
- More defensive asset classes, represented here by IA Strategic Sterling Bond, have this time provided some protection and uncorrelation
During times like this, emotion and irrationality will drive rash investment decisions, however we will try to remember that risks often bring rewards. Markets have shifted rapidly from ‘business as usual’ to ‘we’re all doomed and there’s no end in sight’ and we have seen many times similar capitulations during times of stress.
What usually happens in response to such events, in relatively short order, is two important factors:
- Some form of rational thought returns, mitigating factors are factored in
- Policymakers step up (we’ve already seen signs of this) and coordinate a response
LOCKDOWN UNCERTAINTY: 8th April 2020 to 31st December 2020
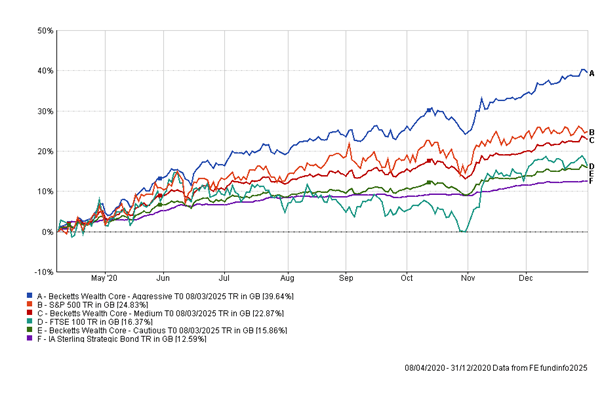
A combination of the above factors gave rise to a significant and rapid recovery of assets values in 2020.
We take comfort that the current conditions are entirely man made. The global economy has entered this policy change in a fairly healthy state and there should be headroom for fiscal stimulus.
It is for these reasons that we continue to advocate calm and avoid knee-jerk reactions. A swift recovery of asset values could transpire at any time and we sense perhaps close by – although, we should not be surprised to see more volatility too.
We expect that new medium-term trends will emerge and we remain close to events. We’re ready to move and adjust, to capture maximum benefit.